Budget Variance: How FP&A Teams Build a Tighter Reporting Workflow

The budget is set. The month is over. And somewhere between what you planned and what the business actually spent, there's a gap your CFO wants explained by end of week. All you have is a data export, a pivot table, and department heads who take two days to respond to Slack messages.
That's budget variance. Finding it is the easy part. Explaining it, quickly, accurately, with enough detail that no one in the finance review has to ask a follow-up, is where your time actually goes. That work repeats every month in the lead-up to the finance review.
This guide breaks down what budget variance is, how to analyze it in a way that holds up under scrutiny, and how high-performing FP&A teams have built a workflow that stops variance from eating their reporting cycle.
Key Takeaways
- The variance is the easy part. The explanation is where the finance review falls apart.
- Favorable doesn't mean fine. Every variance, in either direction, deserves a second look.
- Internal and external causes demand different responses. Conflating the two produces the wrong fix.
- A percentage threshold without a dollar floor has blind spots. Set both.
- The earlier actuals are available, the more time you have to act on a variance.
What Is Budget Variance?
Budget variance is the measurable difference between a budgeted financial figure and the actual result for the same period. It applies to both revenue and expense lines and is expressed as a dollar amount, a percentage, or both. A variance where your actual revenue exceeds the plan, or where your actual costs come in below budget, is favorable. The reverse is unfavorable.
You use budget variance to monitor financial performance, surface operational problems, and calibrate future forecasts. Done well, it's a strong signal in the finance review. Done reactively, it's a documentation exercise that arrives too late to influence any decision.
Why Budget Variance Matters Beyond the Monthly Report
A variance is only useful if it triggers action. Favorable variances on expenses can signal efficiency or underinvestment. Unfavorable revenue variances can signal missed targets or a pricing problem worth addressing before next quarter.
Most teams read the number, write the explanation, and move on. That's where the value gets left on the table, because variance data tells you something about how the business is actually running, and that information has a shelf life.
Teams that feed variance data back into their planning assumptions tend to produce tighter budgets over time. The discipline compounds: better variance analysis today means fewer surprises in next year's plan.
Types of Budget Variance
Budget variances are classified into distinct categories based on whether the deviation involves revenue, costs, pricing, or volume. Each type points to a different root cause.
| Variance Type | Favorable Condition | Unfavorable Condition |
|---|---|---|
Revenue Variance | Actual revenue > Budgeted revenue | Actual revenue < Budgeted revenue |
Expense Variance | Actual costs < Budgeted costs | Actual costs > Budgeted costs |
Volume Variance | More units sold than planned | Fewer units sold than planned |
Price Variance | Rate deviation improves margin | Rate deviation compresses the margin |
Labor Variance | Lower rate or fewer hours than planned | Higher rate or inefficiency vs. plan |
Revenue Variance vs. Cost Variance
Your organization can post a favorable revenue variance, beating its sales target, while posting an unfavorable cost variance if expenses grew faster than revenue. Analyzing both sides of the income statement together is essential; a favorable number in one category can mask a structural problem in another.
Volume Variance and Price Variance
Volume variance isolates the effect of selling more or fewer units than planned. Price variance isolates the effect of a rate change. A volume shortfall often points to sales execution or demand. A pricing deviation points to commercial strategy. Separating the two keeps your root-cause analysis, and your corrective response, pointed in the right direction.
Budget Variance Formula: How to Calculate It
Dollar Variance:
Budget Variance = Actual Amount − Budgeted Amount
Percentage Variance:
Budget Variance % = [(Actual Amount − Budgeted Amount) / Budgeted Amount] × 100
Note: For expense lines, many teams reverse the formula (Budgeted minus Actual) so that spending below budget produces a positive number, consistent with the favorable convention. Pick one approach and apply it consistently across every report.
Worked Example: Step-by-Step
- Pull the budgeted figure for the line item and period (e.g., Q2 marketing spend: $80,000)
- Pull the actual figure from your accounting system for the same line and period (e.g., Q2 actual: $91,500)
- Apply the formula: $91,500 − $80,000 = $11,500 variance
- Calculate percentage: ($11,500 / $80,000) × 100 = 14.4 percent
- Label it: Because the actual expense exceeded the budget, this is an unfavorable expense variance
- For a revenue example: projected Q2 revenue of $150,000 against actual revenue of $165,721 yields a $15,721 favorable variance, or 10.5 percent.
Dollar Variance vs. Percentage Variance: Which One to Lead With
Dollar variance tells you the absolute size of the gap. Percentage variance tells you how material it is relative to the plan. Neither one tells the full story on its own. A percentage without a dollar amount can make a small variance look alarming. A dollar amount without a percentage can make a large one look manageable.
A $500 variance on a $600 budget line (83 percent) demands more attention than a $50,000 variance on a $10 million line (0.5 percent). That's the materiality question. Without a defined threshold, you're making that call differently every month, which means your close looks different every month too.
Most teams set materiality thresholds as percentages, paired with a dollar floor, to keep investigation time focused on deviations that actually require management attention. The mechanics of setting those thresholds precisely are covered in our guide on calculating materiality thresholds in accounting.
Your org has an AI mandate. Here's how AI Forward Finance teams are executing it.
Budget Variance: Primary Causes
Variances fall into two broad categories: internal causes, within your control, and external causes, driven by market or environmental forces. Diagnose the correct one before assigning accountability or adjusting next year's budget.
The most common causes you'll encounter:
- Inaccurate forecasting: overly optimistic revenue projections or underestimated cost assumptions baked into the original budget
- Market and cost changes: supplier price increases, commodity swings, or interest rate shifts not anticipated at budget time
- Volume changes: higher or lower demand than projected, affecting both revenue and variable cost lines simultaneously
- Timing differences: revenue or expenses recognized in a different period than planned, creating a temporary variance that reverses in subsequent months
- Operational inefficiency: process failures, rework, or productivity shortfalls driving labor or material costs above plan
- Strategic decisions made post-budget: mid-year headcount additions, software expansions, or program cancellations that weren't in the original plan
- Employee error or fraud: unauthorized spending or accounting mistakes that inflate actual expense figures
Why the Internal vs. External Distinction Changes Your Response
Internal causes (poor forecasting, operational gaps, unplanned investment) call for changes to processes or accountability. Getting that diagnosis wrong is expensive. Holding a team accountable for a variance driven by a supplier price increase they couldn't have predicted just erodes trust in the review process.
External causes (input cost inflation, shifts in the demand environment, regulatory surprises) call for budget reforecasting. Conflating the two produces the wrong response.
How Timing Differences Distort Your Budget vs. Actual Picture
A large unfavorable variance in March may reflect a vendor invoice that was expected in February. The full-year position is unchanged, but the monthly report looks alarming. Flag timing-driven variances explicitly, separated from structural ones, so leadership isn't chasing problems that don't exist.
How to Do a Budget Variance Analysis
Budget variance analysis is the systematic process of comparing actual financial results to the budget, categorizing the deviations, investigating root causes, and communicating findings to decision-makers. In practice, that process is only as good as the speed at which you can move through it.
Done well, it transforms a static budget document into a live management tool. Done as a documentation exercise at the tail end of close, it produces explanations that are accurate but too late to shape decisions.
- Collect data: pull actuals from your ERP aligned to the budget at the right level of granularity: department, cost center, line item
- Calculate variances: apply dollar and percentage formulas to every material line item
- Apply materiality filters: focus investigation on variances exceeding your threshold (commonly 5–10 percent per line item, or a defined dollar floor)
- Categorize by type and cause: favorable or unfavorable, revenue or expense, internal or external, structural or timing
- Write variance commentary: factual explanations that cover what happened, why it happened, and what action is being taken
- Recommend corrective action: budget adjustments, reforecasts, or operational changes based on your findings
- Update the rolling forecast: incorporate known variances and trends so future periods reflect current reality, not the original plan. McKinsey's research on forecasting finds that CFOs who use rolling forecasts report higher satisfaction with their planning process. The teams that get the most from variance analysis are the ones feeding it back into a live forecast rather than a static annual budget.
Acceptable Variance Thresholds: When to Investigate, When to Move On
Most organizations define materiality thresholds, typically 5 percent to 10 percent per line item, paired with a dollar floor, below which variances are noted but not formally investigated. Where you set that threshold matters as much as having one. Set it too tight and your team spends the reporting cycle investigating rounding differences. Set it too loose and a problem clears the filter unnoticed.
Percentage-only thresholds can let large absolute dollar variances slip through on high-budget lines, so pairing a percentage with a dollar floor covers both types of risk. Once your threshold is set, apply it consistently. A materiality framework that gets adjusted based on how busy close week is stops being a framework and starts being a judgment call. Judgment calls compound into an unpredictable review process.
Variances that exceed the threshold, persist across multiple periods, or sit on high-stakes lines (top-line revenue, headcount, capital expenditure) should be escalated with a root-cause explanation and a recovery plan.
Writing Variance Commentary That Holds Up in the Finance Review
The part of the variance analysis that takes the most time is the explanation. Take a $42,000 software overspend. You pull the data from your planning tool. The GL detail isn't there. You go back to accounting for a breakdown. Wait two days for a reply. Then write it up, by which point you're already behind on the board pack.
Do that across ten material variances. You've lost two days of the reporting cycle to data gathering alone.
That's where the time goes: chasing the data behind the variance. When the actuals you're pulling from are clean and current, the explanation follows quickly. When they're not, you're building a narrative on numbers you can't fully trust.
That matters more than it gets credit for. Variance commentary builds or erodes your credibility as a strategic voice in the room. When leadership starts coming to you with questions instead of corrections, FP&A has moved from reporting to decision-making.
Favorable vs. Unfavorable Budget Variance: What Each Signals
The terms “favorable” and “unfavorable” replace “positive” and “negative” for good reason: a positive dollar figure on an expense line is bad news.
| Scenario | Budget | Actual | Variance | Favorable or Unfavorable? |
|---|---|---|---|---|
Sales Revenue | $500,000 | $535,000 | +$35,000 | Favorable |
Operating Expenses | $200,000 | $227,000 | +$27,000 | Unfavorable |
Cost of Goods Sold | $150,000 | $138,000 | −$12,000 | Favorable |
Payroll | $120,000 | $114,000 | −$6,000 | Favorable |
Marketing Spend | $40,000 | $53,000 | +$13,000 | Unfavorable |
Why Favorable Variances Still Require Investigation
A department that comes in under budget on labor may have been understaffed, leaving critical work undone. A business that beats revenue targets by discounting may have earned more dollars while compressing margins, an effect that won't be visible until next quarter. The number looks good. The story behind it doesn't always.
Favorable variances that go unexamined can mask underinvestment or pricing strategy failures just as readily as unfavorable ones.
The Risk of Recurring Unfavorable Variances
An unfavorable variance is a signal. A one-time supply chain disruption calls for a budget adjustment. A persistent forecasting error calls for a process change. Left unaddressed, recurring unfavorable variances erode cash reserves and damage creditor relationships. They also undermine confidence in your budgeting process, at the exact moment you're trying to demonstrate that finance is a strategic function.
That positioning, finance as a strategic function, starts with how you handle the numbers in front of you. The CFOs who get there treat variance data as a strategic management tool rather than a compliance exercise.
From Reactive Documentation to a Proactive Variance Workflow
By the time you're writing the variance explanation, the business event that caused it happened three weeks ago.
The structural problem is data availability. For most FP&A teams, the root cause is data access. Budget vs. actual analysis is only as current as the actuals underneath it. If the accounting close is slow or the data isn't queryable, your variance picture is always lagging.
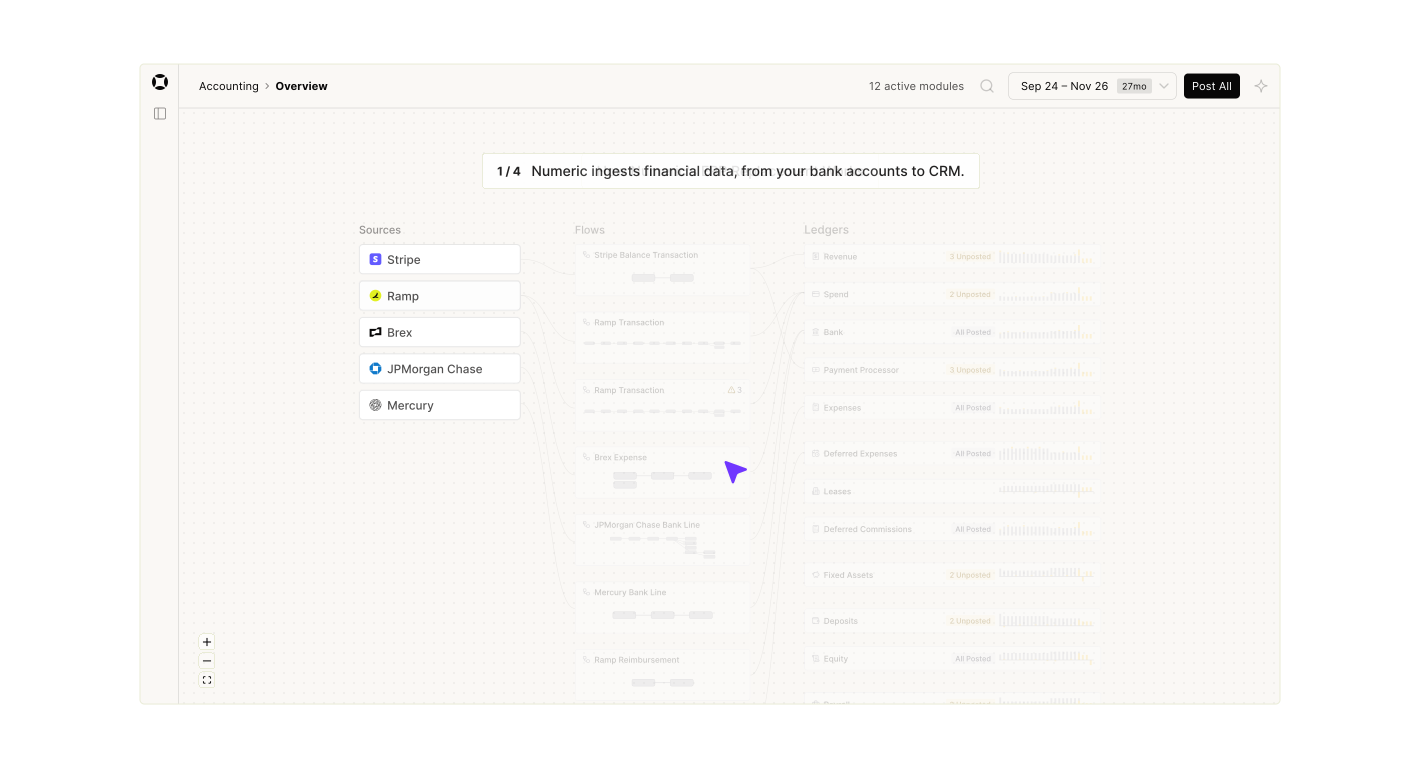
Numeric's ERP replacement, the Financial Data Platform (FDP), built on data-centric accounting, keeps a transaction's dimensions, like department or cost center, attached to the data itself instead of fixed the moment it's entered. FP&A can cut spend a new way after the fact, without a data export project or a request to a NetSuite admin. The context a variance explanation needs is there the moment you ask for it.
Variance Analysis and the Audit Trail Problem
The explanation takes time because the data isn't where you need it when you need it. Variance commentary written from memory, reconstructed from a Slack thread, or pieced together from a spreadsheet someone else built creates real downstream risk. It's six months after the reporting cycle. A CFO asks why a line item jumped in Q2. The person who wrote the explanation has left the company. The Slack thread is buried under months of messages. The Google Doc hasn't been opened since the quarter ended. The answer exists somewhere, just not anywhere retrievable.
That's the documentation problem.
This is especially consequential for teams supporting a business moving toward an audit or preparing for an IPO. The quality of your variance commentary matters. So does whether it's retrievable in a form that holds up under scrutiny. When variance commentary lives in Numeric next to the numbers it explains, the audit trail keeps it retrievable long after the quarter ends.
See what changes when reporting doesn't wait on the ERP. The Financial Data Platform applies dimensions at read time, so a new cut of spend doesn't need a new export.
Get to Clean Actuals Faster
Dependency on accounting is where most FP&A teams lose time. The variance is visible in your planning tool. The explanation lives in the GL. And every time you need transaction-level detail to support a commentary, you're waiting on someone else's timeline.
The FDP keeps accounting and FP&A working off the same live dataset. FP&A can query balances, period comparisons, and transaction detail directly through the Numeric MCP, and cut a variance by department or cost center on demand, without a ticket to accounting or a new export every time the business changes shape.
See the FDP in action. Book a demo and see how dimensional reporting and shared actuals work on your own data.

Frequently Asked Questions
Most organizations define materiality thresholds of 5 percent to 10 percent per line item, paired with a fixed-dollar floor, for example, flagging anything over 7 percent or $25,000.
A $30,000 variance on a $2 million budget line is 1.5 percent, below most percentage thresholds, but still $30,000 worth of investigating. Without the dollar floor, it clears the filter entirely.
Flux analysis compares financial results across two periods, month-over-month or year-over-year, while budget variance analysis compares your actuals to a pre-set plan. Both are used during the month-end close, often together, but they answer different questions. Think of it this way: flux tells you what moved, budget variance tells you whether it should have.
Flux surfaces what changed relative to the last period; budget vs. actual surfaces what changed relative to expectations. A line item can show a small flux variance but a large budget variance if last month was also over plan.
Budget vs. actual analysis is only as credible as the actuals underneath it. If the accounting close is slow, incomplete, or hard to query, your variance picture is always a step behind. Numeric's ERP replacement, the Financial Data Platform (FDP), keeps that data queryable and current, so FP&A can pull balances, transaction detail, and dimensional cuts directly instead of waiting on a close to finish. The close isn't FP&A's job. But the quality of it, and how accessible it is, directly affects yours.
Related Content
Billing and Revenue Management: A Guide for SaaS Finance Teams
Billing and revenue management keeps invoices and ASC 606 revenue tied to one contract. See how contract changes affect both and how to evaluate a solution.
The 9 Best Usage-Based Billing Software Tools for Accounting Teams
Compare the 9 best usage-based billing software tools on pricing, ERP fit, and ASC 606 revenue recognition, starting with Numeric's Billing and Revenue.
Automated ASC 842: From Lease PDF to Audit-Ready Schedule
How to automate ASC 842 lease accounting, from extracting lease terms to the ROU asset, lease liability, and journal entries your auditors can trace.