Expense Allocation in Accounting: From Shared Costs to True Margins (and Why the Usual Methods Break)
Your VP of Engineering emails during close week because $47,000 in facilities costs just landed on her department's numbers, and she wants to know why.
The answer lives in a workbook on someone's laptop, where tab one holds the trial balance export, tab two holds headcount pulled from the HRIS three weeks ago, and tab three holds square footage numbers someone got from the office manager back in 2024. The formula that produced $47,000 spans four cells across two tabs, and the person who built it left in March.
You know the number is right, but you can't show your work in under an hour.
This happens because general ledgers store amounts organized by account and nothing about the operational context that determines how those amounts should be split. The math ends up in a spreadsheet outside the ledger, and the result comes back as a journal entry that strips out how it was calculated. No amount of process discipline fixes that, because the problem is where the work happens rather than how carefully you do it.
Key Takeaways
- Allocation spreads shared costs like rent and software across departments and products, using drivers like headcount and square footage.
- Driver data lives outside the GL, in your HRIS and facilities systems, which is what makes allocation painful.
- Spreadsheets and aggregate JEs fail the same test, since neither can show which transactions and ratios produced an allocated amount.
- Dimension-tagging handles direct costs but stops at shared ones, because you can't tag one rent invoice three ways at entry.
- Opaque allocations are worse than none, since false precision makes bad pricing and headcount calls feel safe.
What Expense Allocation Actually Involves
Expense allocation distributes shared, indirect costs to the departments, products, projects, or customers that benefit from them. The work breaks into three parts, namely the costs you spread, the drivers you spread them by, and the monthly process that does the spreading.
The best finance teams are becoming finance engineers. Get the weekly newsletter.
The Shared Costs That Get Allocated
Most companies allocate from four or five cost pools, starting with facilities and occupancy for rent, utilities, and building services, and IT and software for infrastructure, licenses, and support. HR and people operations covers benefits administration, recruiting, and training, while finance and shared services covers accounting, legal, and procurement. Corporate overhead catches whatever is left, from executive compensation to insurance to anything else that serves the whole company rather than any part of it.
Costs you don't allocate don't disappear, they just sit in an undifferentiated corporate bucket. This means every departmental and product-level P&L you produce is missing part of its true cost.
Allocation Drivers
A driver is a measurable proxy for benefit received. The right driver is the one that tracks how consumption actually varies across recipients.
| Cost pool | Common driver | Why it works |
|---|---|---|
Facilities and occupancy |
Square footage | Space consumed is the cost |
HR, benefits, people ops |
Headcount | Cost scales directly with employees |
Software licenses |
Seat count | Billing is already per-seat |
IT infrastructure and support |
Usage metrics or ticket volume | Consumption varies widely by team |
Corporate overhead |
Revenue share | No better proxy exists for general benefit |
Manufacturing and service delivery |
Activity counts | The basis for activity-based costing |
The catch is that every one of those drivers lives outside your general ledger. Headcount sits in the HRIS, ticket volume in the ITSM tool, and square footage in a facilities system or a spreadsheet the office manager keeps. Your GL holds the costs and none of the information needed to split them, so every allocation starts by assembling data from systems that close on their own schedules.
Cloud and AI spend makes that harder. It's the fastest-growing shared cost at most SaaS companies and the hardest to attribute, and the FinOps Foundation's State of FinOps 2026 report found allocation to be the top priority capability across SaaS, licensing, and data center spend, with attributing AI costs to business units among the hardest problems practitioners report.
The Standard Allocation Process, Step by Step
The monthly workflow is consistent across most teams:
- Identify the shared cost pools for the period and compile their totals from the GL.
- Pull driver data from the HRIS, ITSM, facilities, or CRM systems.
- Define the recipients, whether departments, products, entities, or customers.
- Calculate each recipient's share as total cost multiplied by their portion of the driver.
- Post allocation journal entries debiting the recipients and crediting the pool.
- Reconcile allocated totals back to the original expense so nothing is created or lost.
Step 4 is the one to pay attention to. The calculation happens outside the ledger, using data the ledger never holds, and only the final answer comes back. That's the seam where later questions about the number tend to originate.
Read Architecture for Agentic Accounting on data-centric accounting, what changes when cost pools, drivers, and dimension tags live with the transactions instead of a workbook three systems away.

Why Expense Allocation Matters
Without allocation, shared costs hide in corporate overhead and every department, product, and customer P&L understates what it costs to run. That gap costs you in four ways:
- True margins change decisions. A product line that clears a 60% margin on direct costs alone might clear 35% fully loaded, and those two numbers support opposite calls on whether to invest in it. The same distortion runs through pricing, headcount planning, and vendor rationalization.
- Opaque allocations carry their own risk. A confident wrong number drives worse decisions than an acknowledged gap, and if nobody can verify how $47,000 landed on Engineering, that figure has authority it hasn't earned.
- Transparency changes behavior. A department head who can see their IT charge tracking their team's ticket volume starts asking how to file fewer tickets, while a black box just gets written off as an overhead tax.
- External reporting depends on it. Segment reporting, carve-out statements, and board reporting all require allocation methodologies that are consistent and traceable.
Where Standard Allocation Approaches Break Down
Most teams use one of three approaches, and each breaks down at a different point.
Spreadsheet Models
Spreadsheets are the default for good reasons. They model any structure, cost nothing, and every accountant already knows how to use them.
The problem is that they sit outside the ledger. Because the calculation lives in a workbook separate from the system of record, the GL receives the output and nothing else, meaning none of the logic, none of the driver data, and no link back to the source transactions.
That separation produces a predictable set of failures:
- Version drift. Three copies of the model circulate and nobody is certain which one produced last month's entries.
- Stale driver data. Headcount was pulled on the 3rd, two people transferred on the 12th, and the allocation reflects neither.
- Silent formula errors. A range that doesn't extend to the new department misallocates for months without triggering anything.
- Single-person dependency. One person understands the model, and their vacation moves the close date.
- No audit trail. "Show me how this $47,000 facilities charge was allocated to Engineering" gets answered with a multi-tab file pulling manual inputs from three systems.
Aggregate Allocation Journal Entries
The output of that model is a journal entry that debits receiving cost centers and credits the overhead pool. It ties out, it posts cleanly, and it satisfies the ledger.
It's also opaque by design, because while the GL now knows $47,000 went to Engineering, it has no record of which invoices made up the pool, which square footage figures were used, or which version of the model produced the ratio.
That opacity breaks two things downstream:
- Allocated amounts can't be sliced any further, so when someone asks for that $47,000 broken out by product line or office location, you're back in the spreadsheet redoing the math.
- When drivers or the org chart change, every prior-period entry becomes stale, so restating for comparability means re-running the model once per affected period.
Dimension-Tagging Tools
ERP segments, class tracking, and custom fields are a real improvement over a flat chart of accounts. Tag a transaction with a department at entry and direct costs land where they belong automatically.
Tagging hits its ceiling on shared costs, because it can only describe a transaction as one thing, and a rent invoice benefiting three departments is several things at once. Most systems won't let you tag it 40% Engineering, 35% Sales, and 25% G&A at the point of entry, so the allocation math still has to happen somewhere else.
ERP allocation modules go further and automate the calculation, which is a genuine step up from a workbook. Most still post the result as the same aggregate entry, which means the traceability problem survives the automation.
Why Expense Allocation Keeps Breaking: Flat General Ledgers
What's happening above comes down to one thing. A general ledger stores monetary balances by account. It doesn't hold the operational detail that determines how those amounts should be split, things like headcount, square footage, or usage.
That context lives in other systems, so the logic gets re-run outside the ledger every period. The GL records shared costs without context, trial balances and driver data get exported to a spreadsheet, and the results post back as aggregate entries that strip out the calculation on the way in. The ledger ends up holding allocated amounts nobody can trace, and next month the cycle runs again.
Because the logic, the data, and the output all sit apart from each other, any change means retracing the whole chain by hand. A reorg is the worst version, since preserving comparability means restating historical allocations one period at a time.
Critically, none of this scales well. Three cost pools across four departments on a single driver is a spreadsheet you can maintain. A dozen pools across departments, product lines, customer segments, and geographies is not, because every new dimension multiplies the combinations instead of adding to them.
Gartner found that most CFOs are still early in adopting AI-enabled cloud ERP, held back by data quality and integration complexity rather than by the software itself. Allocation runs into the same wall, since better tools sitting on a ledger that doesn't hold the context won't fix what's underneath.
A Better Approach: Allocation Rules Inside the System of Record
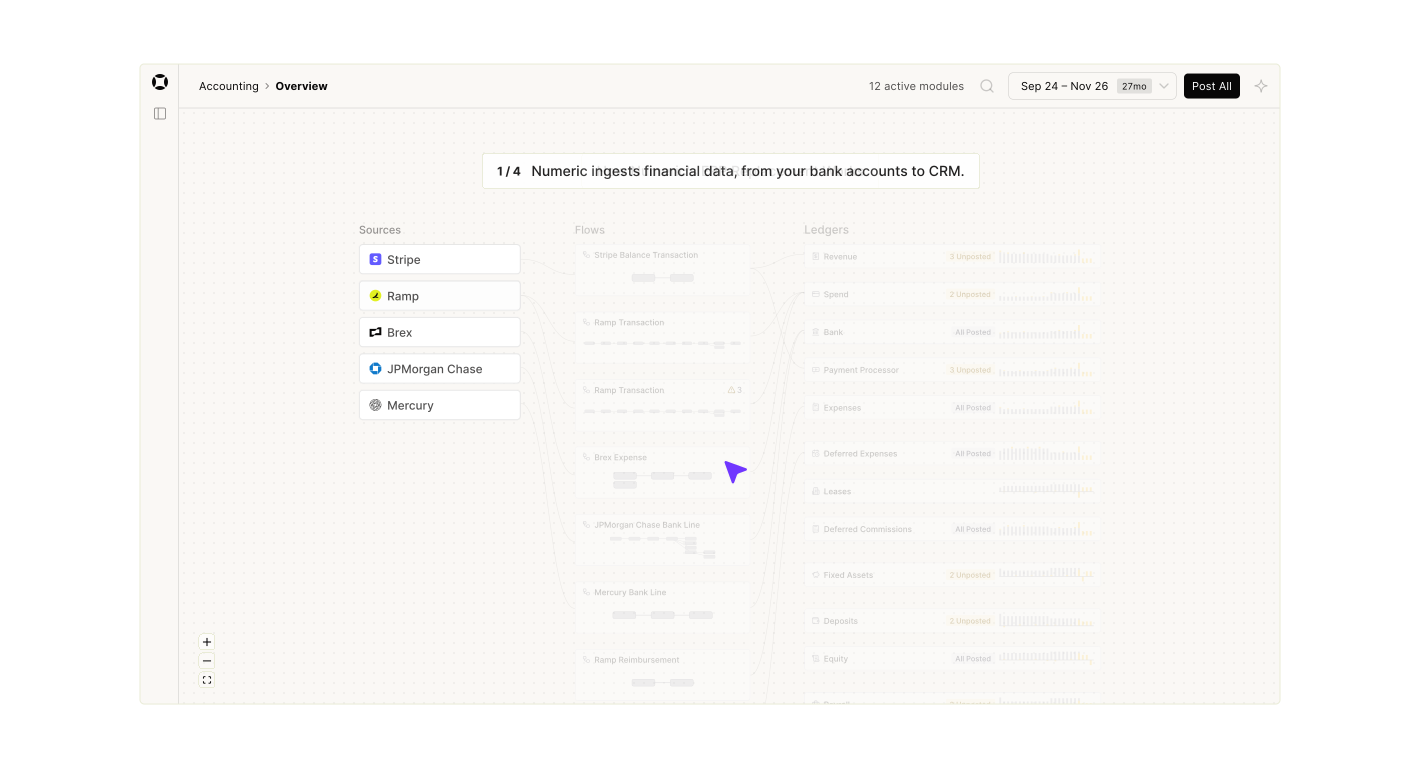
Numeric's view is that allocation belongs inside the ledger, as configuration the system holds, rather than a calculation a spreadsheet produces and hands back as a stripped-down entry.
That's what an ERP replacement changes. Numeric's Financial Data Platform (FDP) is the system of record itself, so the cost pools, drivers, recipients, and dimension tags that determine an allocation live with the transactions they touch instead of in a workbook three systems away. The FDP keeps a financial graph of long-lived objects like invoices and contracts, the relationships among them, and the business events that happen to them, so the context a journal entry would flatten stays attached to every allocated amount.
In practice, that means:
- Rules replace formulas. Cost pools, drivers, and recipients become rules in Flows, the part of the FDP that decides how each transaction gets classified, split, and routed, instead of cell references in a workbook. Each allocation carries the rule that produced it, so the methodology stays in the system when the analyst who set it up moves on.
- Allocated amounts stay tied to their sources. Because the FDP derives the accounting from the underlying objects instead of receiving a stripped-down entry, every allocated amount on a departmental P&L stays traceable to the transactions, rule, and driver data that produced it. Answering the $47,000 question means pointing to the record instead of reopening a workbook.
- Results slice without re-running a model. Dimension tags apply at the transaction level, so the same costs report by department, product, customer, or geography without re-running a model or filing a request to open a new ERP segment. When drivers or the org chart change, prior periods can be re-reported under the new structure, and you decide whether to draft re-class entries.
Because Flows can split a single transaction, one rent invoice can carry its 40/35/25 split across Engineering, Sales, and G&A.
How to Audit and Improve Your Expense Allocation Process
None of this requires buying anything. You can measure what your current allocation setup costs, find where it breaks, and build the case to change it using what you already have.
Audit Your Current Allocation Workflow
Get specific about what allocation costs you today.
- Track hours spent per close on allocation tasks, including pulling driver data, updating the model, posting entries, and answering questions afterward.
- Identify which cost pools and drivers generate the most rework and the most disputes.
- Run the traceability test on your three largest allocated line items. Trace each back toward its source transactions and note exactly where the trail goes cold. That point is your constraint.
Evaluate Your GL Architecture and Tooling
Then check whether your systems make that manual work unavoidable.
- Determine whether your GL can hold the driver context at all, or whether the math is structurally forced outside it.
- If you have an ERP allocation module, check what it posts. Source-linked entries solve the traceability problem, and automated aggregate entries just produce the same black box faster.
- Estimate the rework cost of a reorg or a new product line. If the answer is measured in days, that's a recurring liability rather than a one-time project.
Build the Business Case for Changing It
Put a number on what allocation costs today, then frame the upside in terms a CFO acts on.
- Multiply hours per close by blended rate, then add the cost of delayed closes, unreliable margin data, and audit findings. The month-end close checklist is a good place to see where allocation sits on your critical path.
- Frame the upside as a faster close, fully loaded P&Ls the business trusts, profitability analysis available on demand, and traceability that comes from the system rather than from a person.
See the Financial Data Platform in action. Book a demo with our team to walk through how it works.
Final Thoughts
Expense allocation is technically demanding work, since choosing drivers requires judgment, methodology requires consistency, and both require documentation. None of that goes away with better tooling, and none of it should.
What can go away is the monthly reconstruction around it: the export, the manual driver pull, the model updated by hand each period, and the entry that lands in the ledger without the context behind it. That work exists because the GL doesn't hold what allocation needs, so the math happens in a spreadsheet and comes back as a number that's hard to trace back to its source.
Controllers who separate the accounting judgment from the monthly reconstruction around it evaluate tooling by a harder standard now: whether an allocated number can defend itself. On the FDP, it can. The rule that produced it and the driver data behind it sit right alongside the transactions they touched. Evidence becomes an output of the process instead of a separate project after the close is complete. That's the same $47,000 question from the opening, minus the four cells across two tabs and the analyst who left in March. Schedule a demo and see the trail behind one yourself.
That shift, from defending a number under deadline to talking about what it actually means, is a good part of what turns accounting into a strategic partner instead of a scorekeeper.
Frequently Asked Questions About Expense Allocation
The FDP runs allocation as a native rule inside the system of record instead of a spreadsheet calculation posted back as a journal entry. Cost pools, drivers, and recipients live as configuration tied to the transactions they touch, so every allocated number can be traced back to the rule and driver data that produced it, without re-running a spreadsheet model each time drivers or the org chart change.
Expense allocation is the process of distributing shared, indirect costs, like rent, IT, or corporate overhead, to the departments, products, or customers that benefit from them, using a measurable driver such as headcount or square footage.
Square footage for facilities and occupancy, headcount for HR and people costs, seat count for software licenses, usage or ticket volume for IT, and revenue share for general corporate overhead.
Because they sit outside the general ledger. The GL receives only the output, not the logic or driver data behind it, which creates version drift, stale driver data, and no audit trail back to source transactions.
An allocation journal entry posts once shared costs are calculated and split across recipients, typically debiting the receiving cost centers and crediting the overhead pool for the period.
Most teams run allocation monthly as part of the close: compiling cost pools, pulling driver data, calculating each recipient's share, posting entries, and reconciling back to the original expense.
Related Content
Automated ASC 842 Lease Accounting: From Lease PDF to Audit-Ready Schedule
How to automate ASC 842 lease accounting, from extracting lease terms to the ROU asset, lease liability, and journal entries your auditors can trace.
ERP for SaaS: How to Choose an Accounting System Built for Subscription and Usage Revenue
A guide to choosing an ERP for SaaS, covering ASC 606 revenue recognition, usage-based billing, multi-entity, reporting, and a checklist for vendor demos.
Numeric vs. Maxima: Which AI Close Platform Fits Your Team?
Numeric and Maxima both automate close work. Compare how each handles reconciliations and cash matching, who owns the rules, and when each one fits.